
How to Calculate FIFO and LIFO
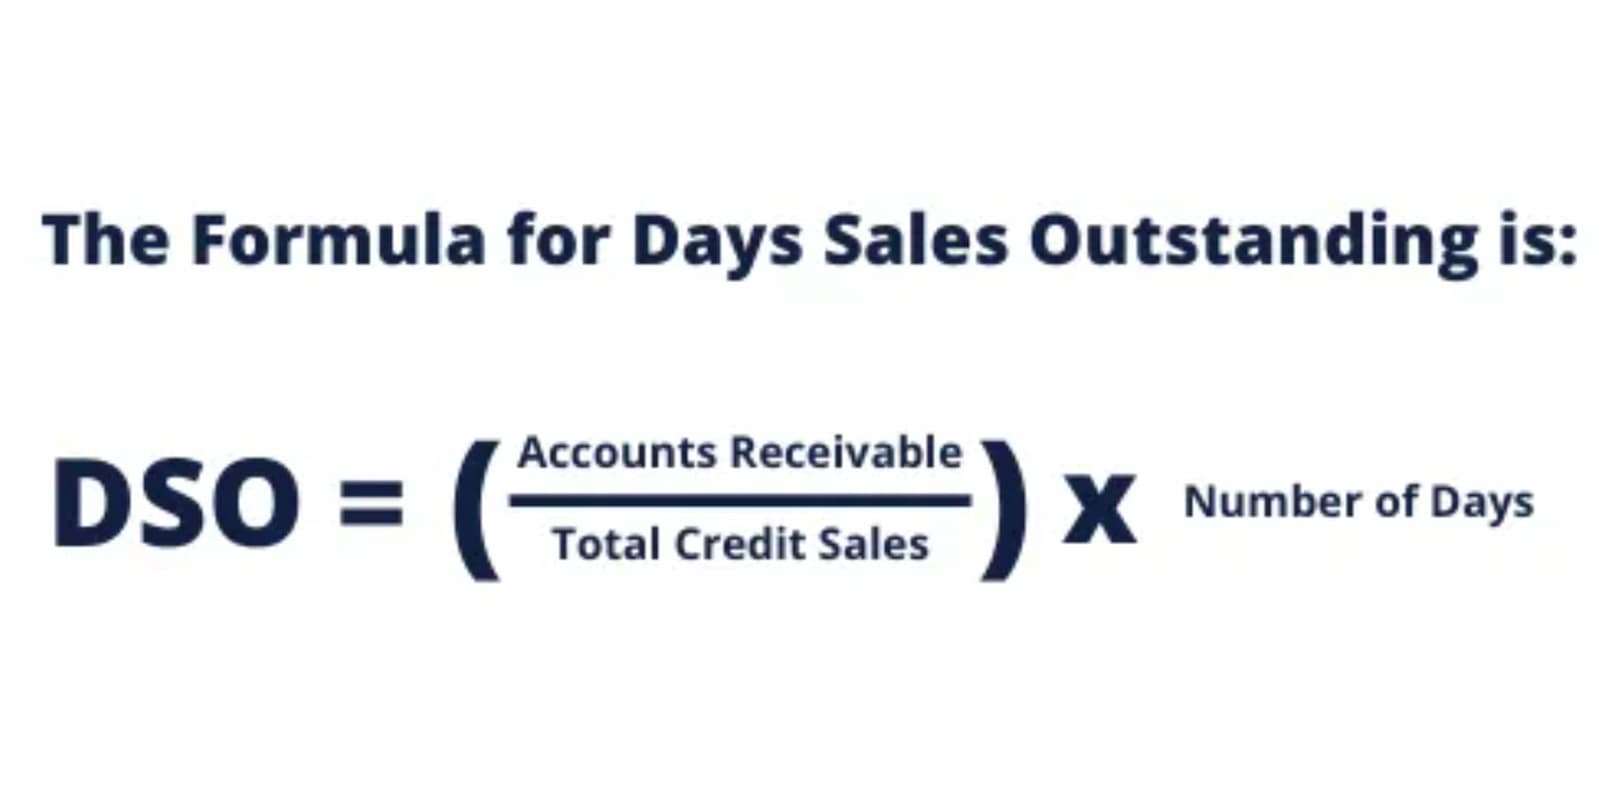
Please note how increasing/decreasing inventory retained earnings prices through time can affect the inventory value. During the CCC, accountants increase the inventory value (during production), and then, when the company sells its products, they reduce the inventory value and increase the COGS value. Here’s a summary of the purchases and sales from the first example, which we will use to calculate the ending inventory value using the FIFO periodic system.
Which financial ratios does FIFO ending inventory calculation affect?
- This means that the ending inventory balance tends to be lower, while the cost of goods sold is increased, resulting in lower taxable profits.
- Not suitable for year-end reporting or official financial statements.
- This increased tax burden can strain cash flow, limiting your business’s ability to reinvest or pay down debt.
- The FIFO method assumes the first products a company acquires are also the first products it sells.
- The company makes a physical count at the end of each accounting period to find the number of units in ending inventory.
- If you operate a retailer, manufacturer, or wholesale business, inventory may require a large investment, and you need to track the inventory balance carefully.
The FIFO inventory method assumes that the oldest goods purchased are the first to leave the company as sales occur. The first in, first out (FIFO) method of inventory valuation is a cost flow assumption that the first goods purchased are also the first goods sold. In most companies, this assumption closely matches the actual flow of goods, and so is considered the most theoretically correct inventory valuation method. The FIFO flow concept is a logical one for a business to follow, since selling off fifo equation the oldest goods first reduces the risk of inventory obsolescence.
How to Calculate FIFO With Example
Businesses using the LIFO method will record the most recent inventory costs first, which impacts taxes if the cost of goods in the current economic conditions are higher and sales are down. This means that LIFO could enable businesses to pay less income tax than they likely should be paying, which the FIFO method does a better job of calculating. The FIFO method is the first in, first out way of dealing with and assigning value to inventory. It is simple—the products or assets that were produced or acquired first are sold or used first. With FIFO, it is assumed that the cost of inventory that was purchased first will be recognized first. FIFO helps businesses to ensure accurate inventory records and the correct attribution of value for the cost of goods sold (COGS) in order to accurately pay their fair share of income taxes.
FIFO Method During Inflation
Ending inventory, also known as closing inventory or closing stock, represents the total value of your unsold products at the end of a specific accounting period. While LIFO produces a lower tax liability, the FIFO method tends to report a higher net income, which can make the company more attractive to shareholders. It also reports a higher value for current inventory, which can strengthen the company’s balance sheet.
How to Calculate COGS in the FIFO Method?
- Lenders often review ending inventory as a key balance sheet metric when considering business loan applications.
- Thus, items still in inventory are the most recently acquired or made (IAS 2.27).
- The FIFO (First In, First Out) method is a fundamental concept in financial accounting and inventory management.
- Now that we have ending inventory units, we need to place a value based on the FIFO rule.
- In this section, we compare FIFO with other common inventory valuation methods to help businesses determine the best approach for their specific needs and circumstances.
The FIFO method avoids obsolescence by selling the oldest inventory items first and maintaining the newest items in inventory. The actual inventory valuation method used doesn’t have to follow the actual flow of inventory through a company but it must be able to Airbnb Accounting and Bookkeeping support why it selected the inventory valuation method. By using WAC, you can simplify your inventory valuation process while providing a consistent basis for financial reporting. However, be aware of its limitations during periods of significant price changes in your inventory costs.
- Calculating the FIFO (First-In, First-Out) cost of goods sold is a key skill for businesses managing inventory.
- FIFO can lead to an improved inventory turnover rate, as it encourages the movement of older stock first.
- Proper recording ensures COGS is accurately reflected on the income statement, affecting gross profit, operating income, and net income.
- However, during periods of declining prices, FIFO may result in higher COGS and lower profitability.
- With FIFO, when you calculate the ending inventory value, you’re accounting for the natural flow of inventory throughout your supply chain.
This will reduce your Cost of Goods Sold, increasing your net income. You will also have a higher ending inventory value on your balance sheet, increasing your assets. This can benefit early businesses looking to get loans and funding from investors. FIFO is calculated by adding the cost of the earliest inventory items sold. The price of the first 10 items bought as inventory is added together if 10 units of inventory were sold.